The National Private Lenders Association’s (NPLA) October 2026 Private Lending Market Report shows higher interest rates, a growing split between RTL and DSCR demand, and rising concern about loan performance. The report combines loan data from Private Lender Law (PLL) with survey responses from NPLA members on residential transition loans (RTL) and debt service coverage ratio (DSCR) loans. Rates rose in both categories, while member sentiment held steady.
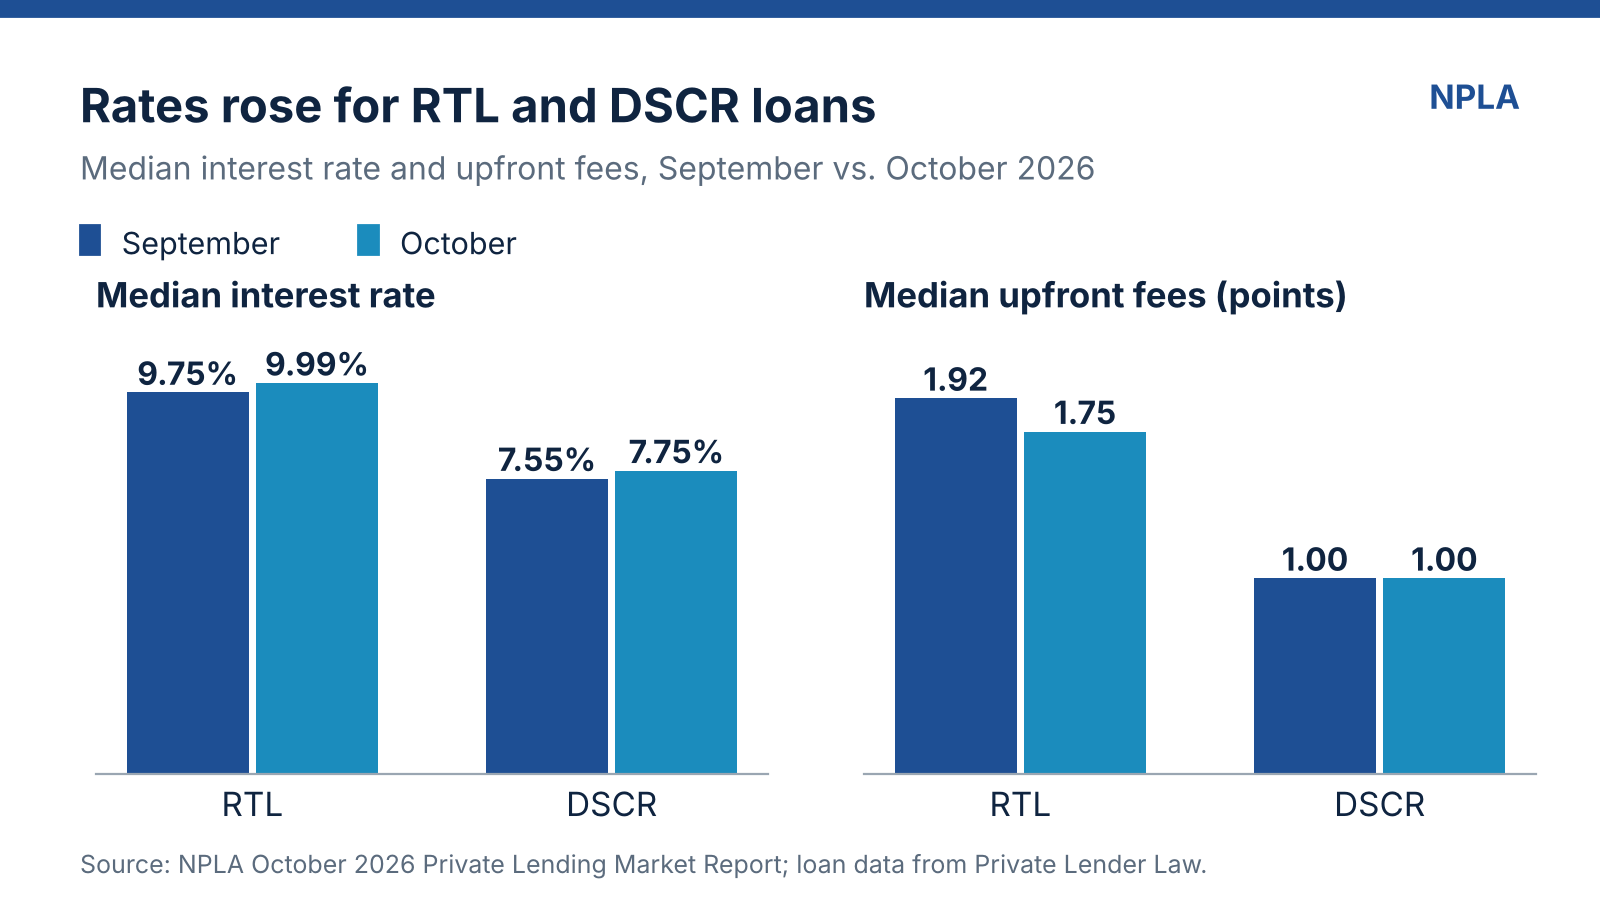
The median RTL interest rate rose to 9.99% in October from 9.75% in September, an increase of 24 basis points. The median DSCR rate rose 20 basis points, from 7.55% to 7.75%.
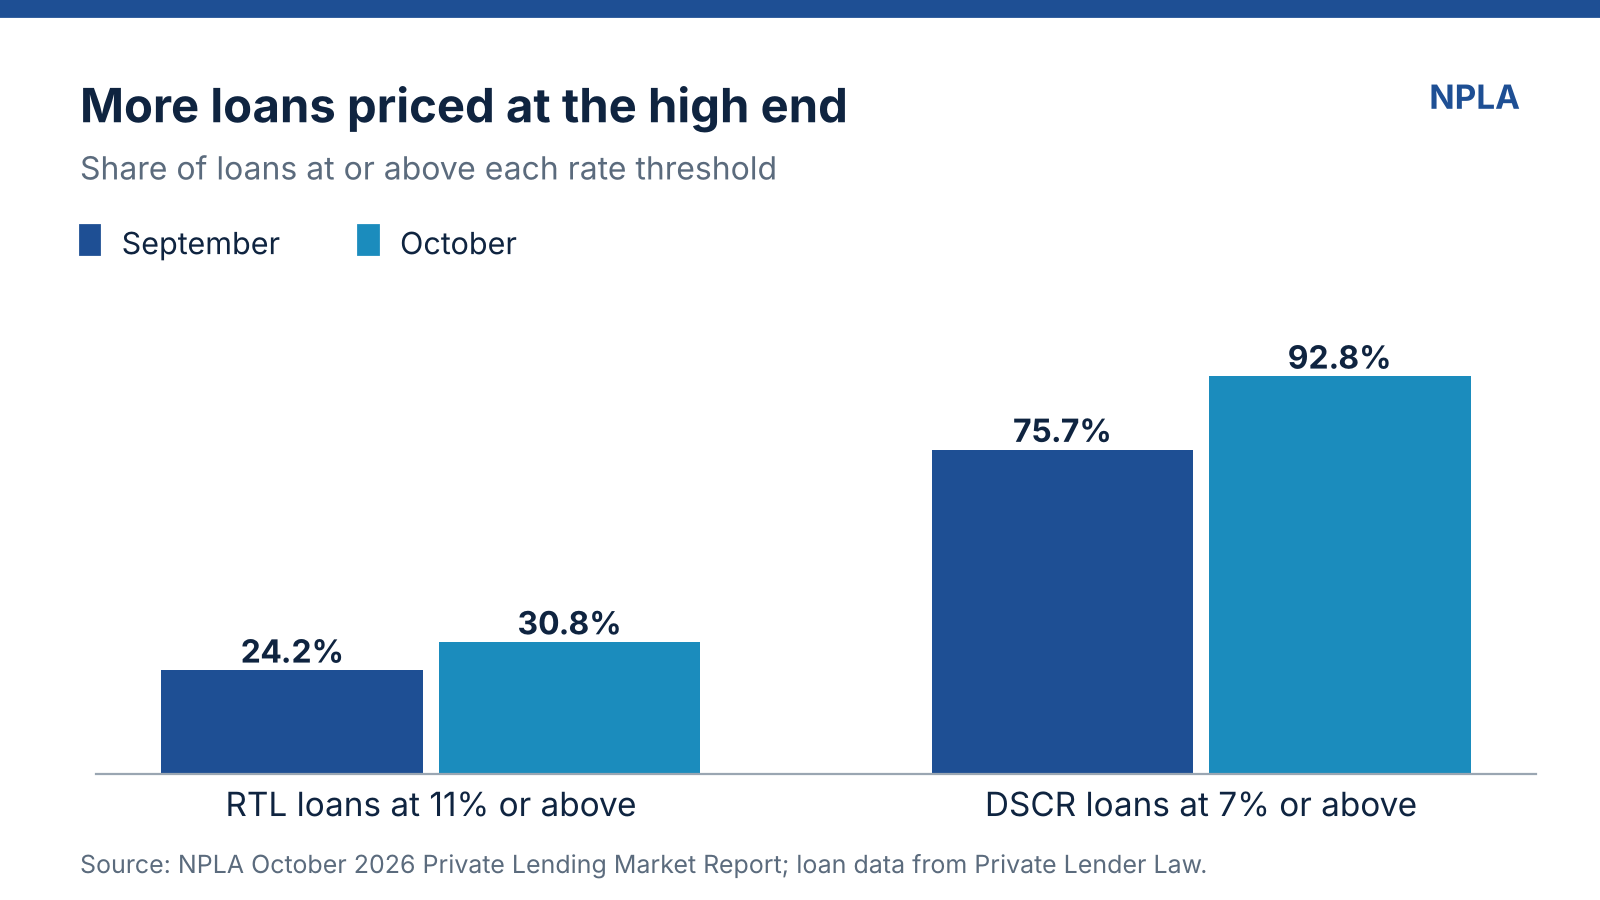
Pricing moved higher across the board. The share of RTL loans priced at 11% or above increased from 24.2% to 30.8%. For DSCR loans, the share priced at 7% or above climbed from 75.7% to 92.8%.
Median RTL fees fell from 1.92 points in September to 1.75 points in October. Median DSCR fees were unchanged at 1.00 point. RTL rates went up while fees came down. DSCR rates went up with no change in fees.
RTL demand held steady at 6.60 out of 10, compared to 6.59 in September. More than half of respondents (51.2%) reported higher RTL lending activity, up from 35.8% the previous month, and 41.9% reported rising investor demand for RTL loans.
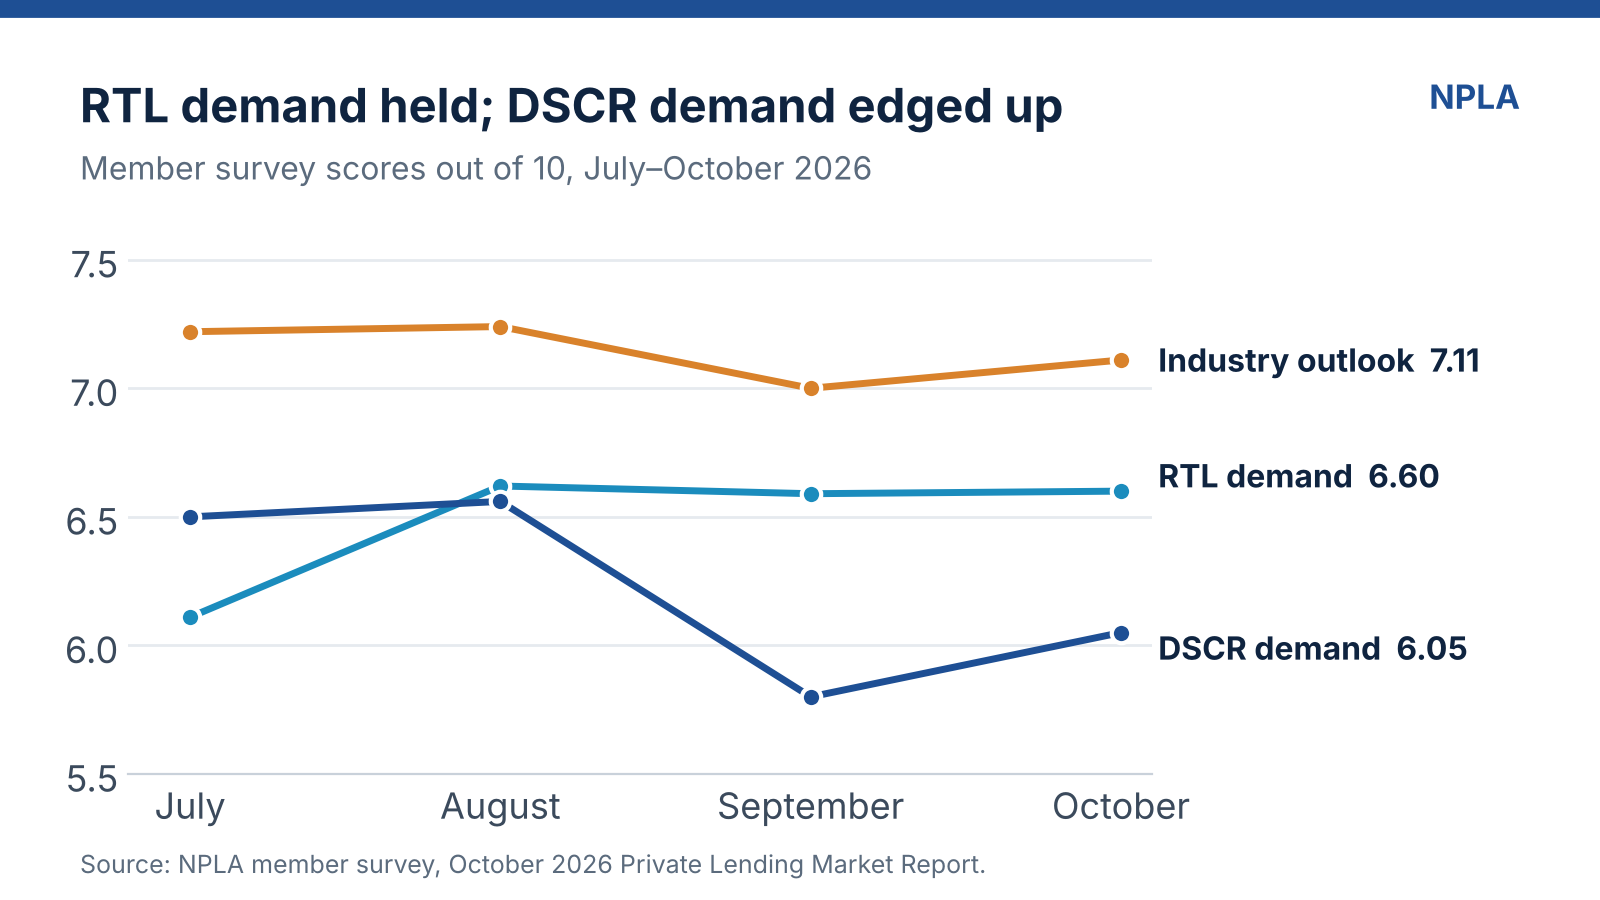
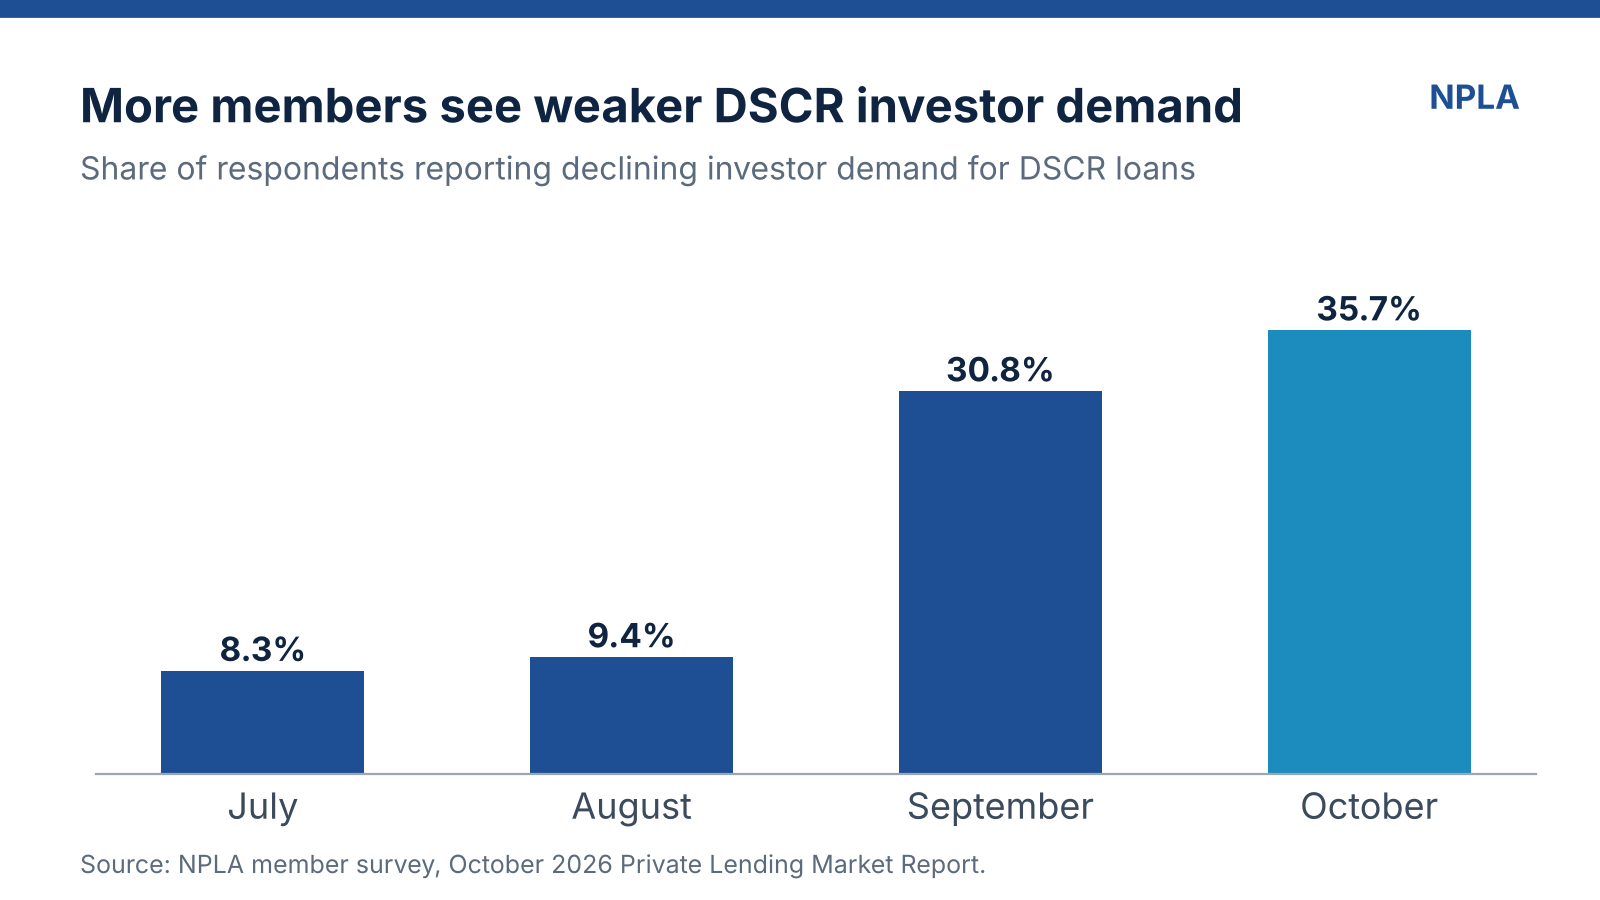
DSCR demand rose to 6.05 from 5.80 in September, though it remains below July (6.50) and August (6.56) levels. Investor demand moved the other way. The share of members reporting declining investor demand for DSCR loans rose to 35.7% in October, up from 30.8% in September, 9.4% in August and 8.3% in July. The same decline showed up among lenders who answered the survey both earlier this year and in October. So the shift isn’t explained by a change in who responded.
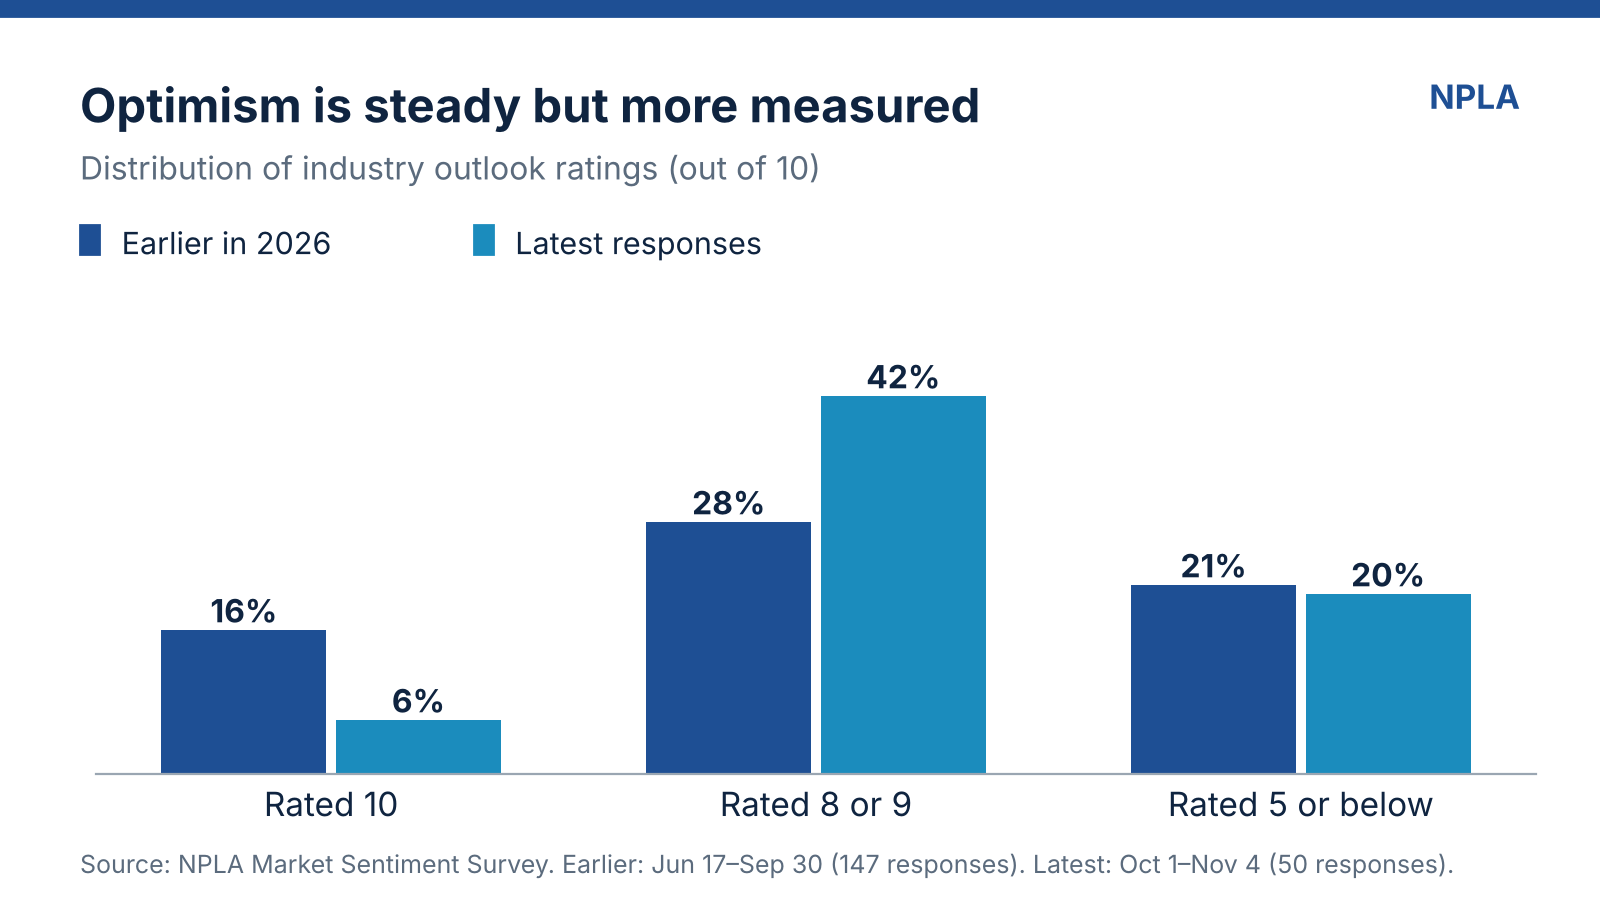
Members rated their overall industry outlook at 7.11 out of 10 in October, up from 7.00 in September. The average held steady, but the spread of responses changed. Compared with earlier this year, fewer lenders rated their outlook a 10 (6%, down from 16%), and more rated it an 8 or 9 (42%, up from 28%). Lenders are still optimistic, but fewer are highly optimistic.
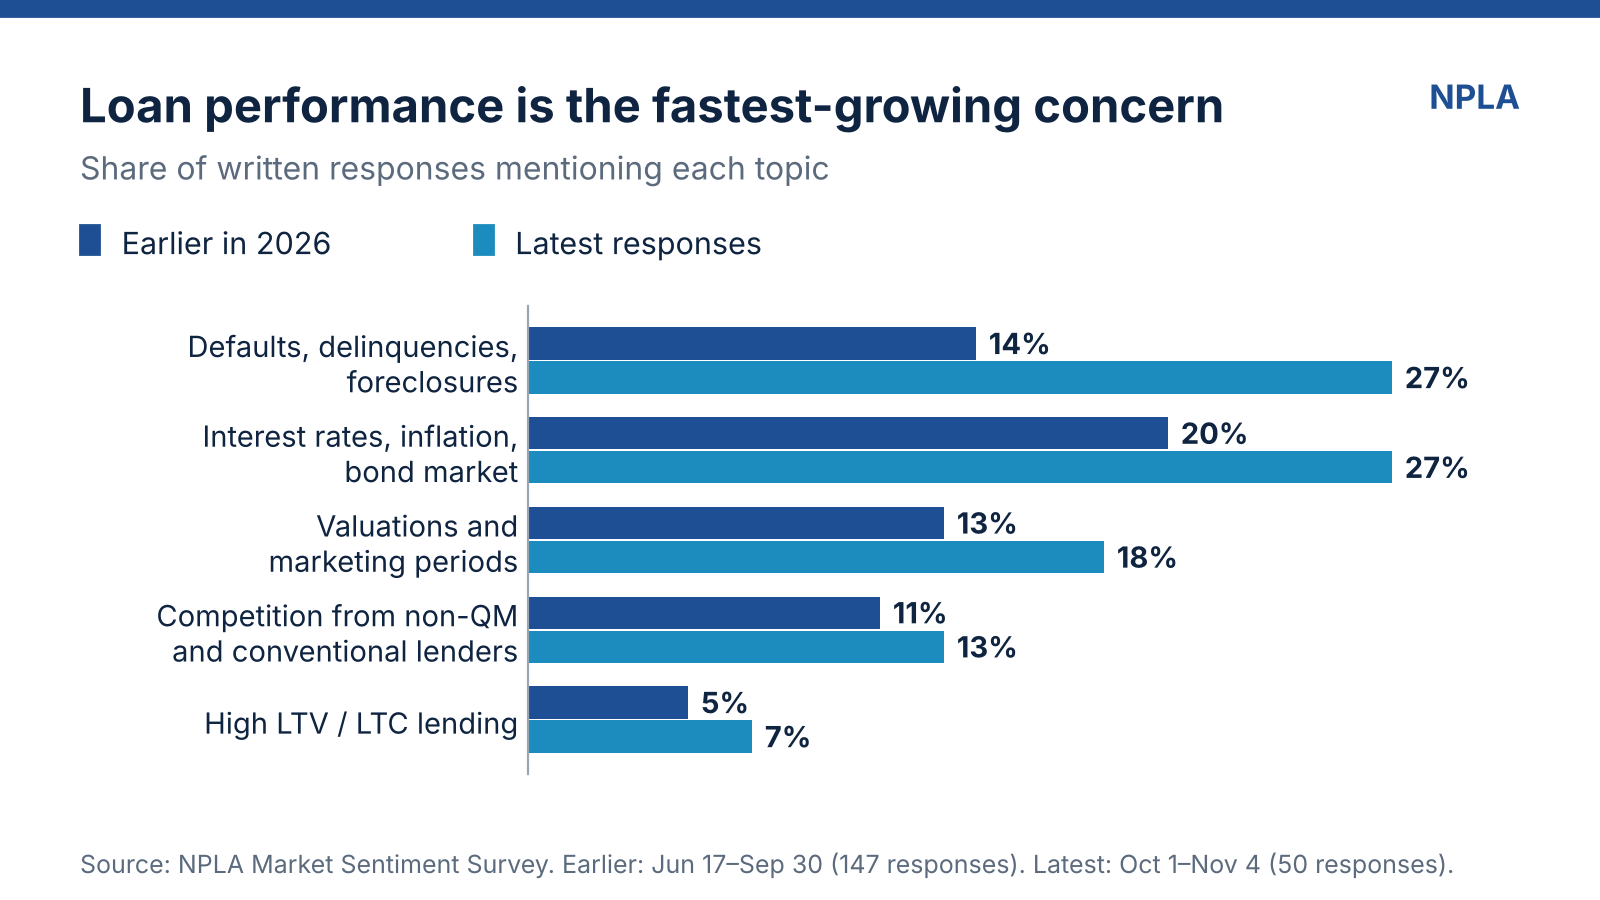
Many lenders are worried about defaults and delinquencies, but most are not yet seeing poor loan performance. Some markets and individual lenders are already seeing spikes in distress. The broader concern is what may come in the near to mid term.
Members’ written comments pointed to four themes:
To learn more about the NPLA, contact Amy Kame at [email protected].